I canceled my traditional health insurance. 😳
I know how that sounds. So let me be clear right away: I didn’t “go uninsured,” and this wasn’t a reckless decision. It was actually the opposite — one of the most researched, deliberate choices I’ve made about my own healthcare in years.
Why I Made This Choice
For many healthy, informed adults, traditional insurance has become:
- Insanely expensive
- High-deductible
- Rarely used
- Misaligned with how we actually take care of our health
Instead, I’m choosing:
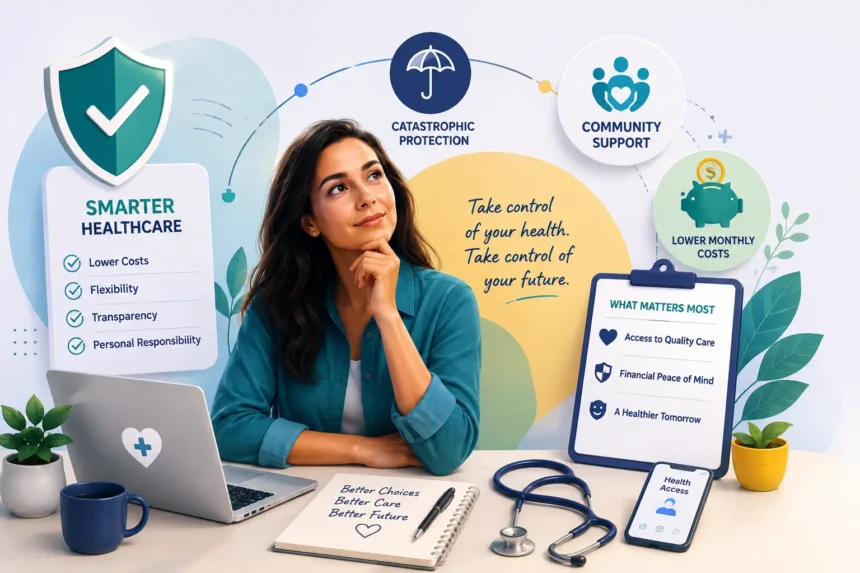
- Lower monthly costs
- Flexibility
- Transparency
- A model that supports personal responsibility and community
So What Did I Actually Do?
To be clear, I didn’t drop coverage and hope for the best. I moved to a two-part strategy:
1. Short-term health insurance (a few months of catastrophic coverage). This is real insurance — it’s just temporary and designed to protect against the big, unpredictable stuff (an accident, a sudden diagnosis, an ER visit) rather than covering routine care. I used it as a bridge while I transitioned into my longer-term plan.
2. A medical cost-sharing plan through Sedera. This is different from traditional insurance. Instead of paying a premium to an insurance company, members contribute monthly into a shared pool, and eligible medical expenses are shared among the community. It’s not insurance in the legal or regulatory sense — there’s no guarantee of payment the way there is with a licensed insurance plan — but for healthy, low-utilization members, it tends to be significantly cheaper and far more transparent about what’s covered and why.
Why This Made Sense For Me
For a lot of healthy, informed adults, traditional insurance has quietly become:
- Insanely expensive
- High-deductible, to the point where it barely functions as “coverage” for everyday care
- Rarely used, especially if you’re not managing a chronic condition
- Misaligned with how people actually engage with their health today — proactive, preventive, and increasingly out-of-network anyway
Instead, I wanted:
- Lower monthly costs
- More flexibility in how and where I access care
- Transparency about what’s actually covered, instead of buried fine print
- A model that puts some responsibility back in my hands, alongside a community absorbing risk together
The Honest Tradeoffs (Because I Owe You That)
I’d be doing you a disservice if I didn’t say this plainly: cost-sharing is not the same as insurance, and it’s not right for everyone.
- It’s not a guarantee. Sharing organizations aren’t regulated the same way insurance companies are, and there’s no legal obligation to pay a claim the way there is with licensed insurance.
- Pre-existing conditions are often excluded or limited, at least for a waiting period.
- This requires you to actually understand your plan. You need to read the guidelines, know what’s eligible, and be comfortable navigating a system that isn’t as standardized as traditional insurance.
- It works best when you’re healthy and low-utilization. If you’re managing a chronic illness, take regular medications, or need predictable specialist care, this is probably not the right fit for you.
Who Might Want to Explore This
- You’re generally healthy and rarely use your insurance beyond a wellness visit
- You’ve been paying high premiums for coverage that barely activates
- You’re financially prepared for the “in-between” months of transition
- You’re comfortable doing your own research and taking on a bit more responsibility for how your care is financed
Who Should Probably Stay With Traditional Coverage
- You have a chronic condition or ongoing treatment needs
- You want predictable, guaranteed coverage without exceptions
- You have a lower tolerance for financial or medical uncertainty
- You haven’t had time to fully research how cost-sharing plans work
My Bottom Line
This isn’t a recommendation to go do exactly what I did. It’s an invitation to actually look at your options instead of renewing on autopilot the way I used to. If you’re paying a lot every month and still avoiding care because of your deductible, it’s worth understanding what else is out there.